Russian Drone Strikes Hit Ukraine Regions as Markets Watch War Risk
Attacks on Zaporizhzhia and Odesa, including port and civilian infrastructure, keep geopolitical risk in focus for equity investors.
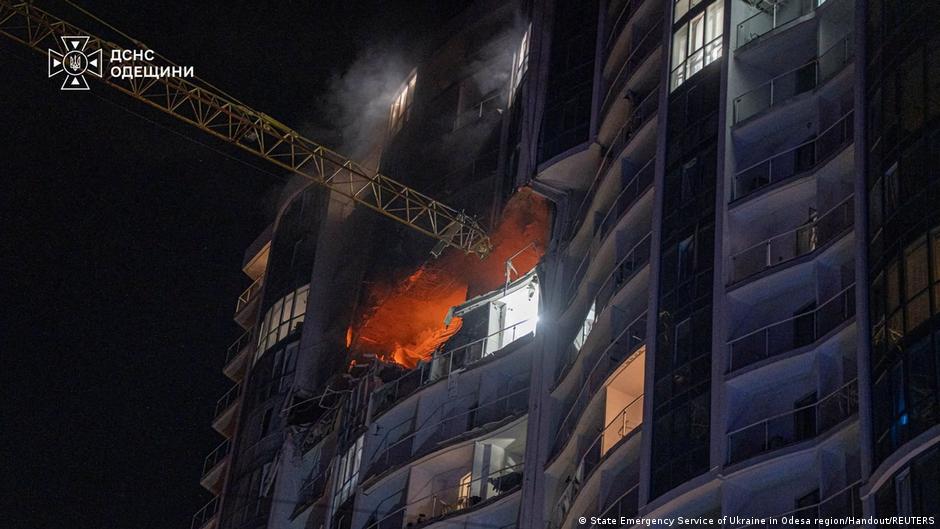
Russian attack drones struck Ukraine’s Odesa and Zaporizhzhia regions overnight on September 27, leaving at least three civilians dead and four others wounded in Zaporizhzhia, according to preliminary information cited by regional authorities. The attacks also hit port and civilian infrastructure in the Odesa region, an area closely watched by markets because of its role in trade flows and Ukraine’s access to the Black Sea and Danube corridor.
For Wall Street, the immediate market question is not a single headline reaction but the persistence of geopolitical risk around energy, agriculture, shipping, defense spending, and European security exposure. The latest strikes underscore that the war continues to affect infrastructure viewed as economically sensitive, even when the direct human and local damage is the central fact of the event.
Acting head of the Zaporizhzhia military administration Mykhailo Semikin said Russian forces struck the settlement of Kamyshevakha and the village of Novotavriiske. Preliminary data showed three civilians killed and four wounded. In Novotavriiske, Russian forces attacked a vehicle traveling through the village, Semikin said. After the strike, the car caught fire, and a man and a woman died at the scene.
Preliminary information from Ukrainian regional authorities said three civilians were killed and four others were injured in Zaporizhzhia region.
Authorities also reported damage in Kamyshevakha, where one house was destroyed and several neighboring homes were damaged. The source account did not provide further details on the identities of the victims or the scale of material losses beyond the residential damage described by officials.
Odesa Infrastructure Remains in Investor Focus
In Odesa region, Russia struck port and civilian infrastructure in the city of Kiliia, according to the Izmail district administration. Preliminary information indicated that no one was injured there. A fire that broke out at the site of the strike was extinguished by emergency services.
Kiliia’s location in Odesa region gives the attack broader relevance for investors tracking Ukraine-related risk across commodity and transport markets. Odesa has repeatedly been important in market discussions because disruption to port and civilian infrastructure can affect expectations around logistics, grain movement, insurance costs, and regional trade resilience. The source article did not report any interruption to shipping, export flows, or port operations from the latest strike, and no such impact should be assumed from the available information.
Still, equity desks tend to treat renewed attacks on port infrastructure as part of a wider risk mosaic. Agricultural traders, shipping-linked equities, insurers, European industrial names, and energy-sensitive sectors can all be affected when investors reassess regional instability. The latest report adds to the kind of background risk that can influence sector rotation even without producing a clear single-stock catalyst.
Sector Rotation Rather Than a Single-Stock Event
Because the reported strikes did not include claims about corporate assets, listed companies, production facilities, or export volumes, the direct read-through for individual stocks is limited. A disciplined equity research view would therefore frame the event as a geopolitical-risk input rather than as a company-specific driver. Defense contractors, energy producers, fertilizer and grain-linked companies, marine transport names, and European banks with regional sensitivity are the areas investors typically monitor when conflict headlines intensify.
In U.S. markets, war-related headlines can support demand for defense and security-linked equities if investors expect sustained government spending. Energy shares may also attract attention if traders perceive heightened risk to regional supply or transport routes. Agricultural names can move when investors focus on grain availability or Black Sea logistics, although the latest source report contains no fresh data on crop exports or trade volumes.
Conversely, investors may rotate away from cyclical or Europe-exposed assets when geopolitical risk rises, particularly if headlines point to infrastructure vulnerability. That kind of shift is often expressed through exchange-traded funds and sector baskets rather than direct trading in companies tied to a single event. Trading volumes can increase around defense, energy, shipping, and agricultural commodity proxies during such periods, but the source material does not provide market-volume data for this episode.
For equity research teams, the key distinction is between confirmed operational disruption and headline risk. The confirmed facts in this case are the reported casualties in Zaporizhzhia, the attack on a moving vehicle in Novotavriiske, residential damage in Kamyshevakha, and strikes on port and civilian infrastructure in Kiliia with no reported injuries there. The unconfirmed market variables include whether logistics were interrupted, whether exports were delayed, whether insurance or freight costs changed, and whether any listed companies faced direct exposure.
Risk Premium Stays Attached to the War
The persistence of attacks across multiple Ukrainian regions keeps a geopolitical risk premium attached to assets exposed to Eastern Europe and the Black Sea trade environment. That premium does not move evenly. Some sectors may benefit from higher perceived security spending or commodity risk, while others may face pressure from uncertainty, inflation concerns, or weaker risk appetite.
The latest overnight strikes, as reported by Ukrainian officials, are therefore likely to be read by markets as another reminder that the conflict remains active and economically relevant. The human toll in Zaporizhzhia is immediate and concrete. The market impact is more indirect: investors will watch whether infrastructure damage in Odesa region translates into measurable disruption, whether commodity prices react, and whether trading flows show renewed preference for defense, energy, and other risk-sensitive sectors.
Until additional operational or market data emerges, the most defensible Wall Street interpretation is cautious rather than dramatic. The event reinforces existing geopolitical concerns but does not, on the facts available, establish a new company-specific earnings or revenue impact. For traders and analysts, that means monitoring sector-level moves, commodity-linked equities, and European exposure while separating confirmed damage from speculative market narratives.