Berlin Left Party Win Puts Housing Policy Risk Back on Investors’ Radar
The Berlin election result raises policy uncertainty for real estate investors, while broader Wall Street exposure appears limited for now.
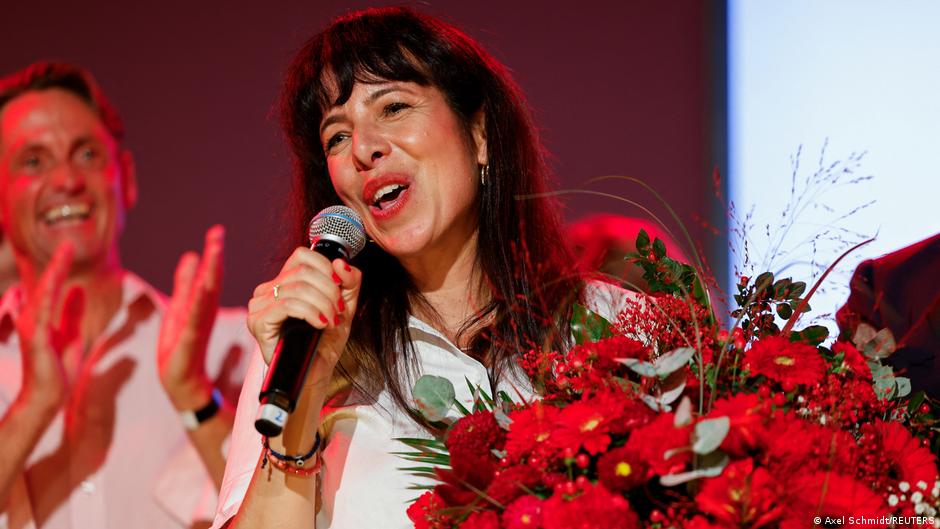
Berlin’s Left Party has won first place in elections to the city’s House of Representatives, a result that is likely to be read by investors less as a national market shock than as a renewed policy risk signal for housing, infrastructure and companies with exposure to the German capital.
According to official preliminary results released overnight into Monday, September 21, the Left Party received 25.7% of the vote in the election held on September 20. That represented a gain of 13.5 percentage points compared with the 2023 election. The Christian Democratic Union, the party of German Chancellor Friedrich Merz, came second with 18.8%.
The far-right Alternative for Germany placed third with 16.3%, followed by the Greens on 14.3% and the Social Democratic Party on 12.1%. The left-populist Sahra Wagenknecht Alliance, with 4.7%, and the liberal Free Democratic Party, with 2.5%, failed to clear the 5% threshold required to enter the Berlin parliament.
In seat terms, the Left Party is set to hold 47 seats in the new House of Representatives, followed by the CDU with 35, AfD with 29, the Greens with 26 and the SPD with 22. Voter turnout was 74.2%.
Housing Stocks Face the Clearest Read-Through
For Wall Street, the most direct market angle is not the headline party ranking itself, but what it could mean for listed property companies, banks with commercial real estate exposure and funds holding German residential assets. The Left Party and the Greens support implementing a 2021 city referendum that called for the expropriation of more than 200,000 apartments from large housing companies. The SPD opposes that plan, making coalition talks potentially difficult.
That divide matters because Berlin housing policy has long been a source of headline risk for investors. Any renewed push toward expropriation could sharpen investor focus on German residential landlords and the valuation discount already attached to regulated urban housing markets. The source article does not identify specific listed companies, share-price moves or trading volumes, so any stock-level reaction would need to be assessed separately in live market data. Still, the sector read-through is clear: real estate names with Berlin exposure may attract closer scrutiny from equity analysts and portfolio managers.
The political math also points to a market narrative centered on negotiation risk rather than immediate implementation. Potential coalition partners for the Left Party are seen as the Greens and the SPD, but the parties differ on housing policy and other issues. That means investors are likely to watch the coalition agreement more closely than the raw vote result. A compromise that waters down expropriation would limit pressure on the sector; a firm commitment to move ahead would increase uncertainty around asset values, legal timelines and capital allocation.
“Berlin residents have given us a clear mandate to lead the city,” Left Party Berlin leader Elif Eralp said.
Eralp has said she expects to take the post of governing mayor of Germany’s capital. If she succeeds, Berlin would move toward a political leadership profile that is more interventionist on housing than many international investors prefer. But the path from election victory to a governing program remains uncertain.
Broader Equity Impact Looks Contained
Beyond real estate, the election result may feed into sector rotation themes already familiar to global investors: pressure on landlords and developers, a more cautious view of regulated utilities and urban infrastructure operators, and potential relative support for companies less exposed to local political intervention. However, the information available in the source does not support claims of broad market moves, changes in trading volumes, or specific Wall Street price action.
For U.S.-based investors, the CDU’s second-place finish may also be watched for signals about Chancellor Merz’s political environment, though this was a Berlin state election rather than a federal contest. The AfD’s third-place result at 16.3% adds another layer to Germany’s fragmented political backdrop, while the failure of the FDP and the Sahra Wagenknecht Alliance to enter the Berlin parliament narrows the coalition arithmetic in the city.
Equity research desks are likely to frame the result around three questions. First, whether the Left Party can form a stable governing coalition with the Greens and SPD. Second, whether housing expropriation becomes part of the binding coalition program. Third, whether controversies emerging during the coalition process weaken the Left Party’s bargaining position.
One such controversy has already surfaced. After voting ended, Issa Remmo, whom German media describe as the head of the well-known Arab-origin Remmo clan, was seen at the Left Party’s election-night gathering in Berlin’s Neukölln district. The party has distanced itself from him, saying the event was open and anyone could attend.
Eralp told ZDF that the party has “nothing to do with organized crime.” Other parties have criticized the Left Party over the episode. Nina Stahr, head of the Greens’ Neukölln branch, demanded explanations from potential coalition partners and linked the issue to talks on forming Berlin’s next government.
Another politically sensitive issue is antisemitism. Eralp has repeatedly emphasized that she wants to support and develop Jewish life in Berlin, but the party faces criticism from possible coalition partners. Greens co-chair Felix Banaszak has already described a coalition with the Left Party as possible, but only if the party demonstrates a clear position against antisemitism.
For markets, these disputes matter because they could complicate coalition talks and delay clarity on the next government’s policy agenda. Until an agreement is reached, the result is best viewed as a localized political risk event with concentrated implications for Berlin housing exposure, rather than a broad catalyst for Wall Street equity markets.